 Skip to content
How a PIP Benefits Lawyer in Dearborn Can Help After a Denial
If your no-fault insurer has delayed, reduced, or denied medical bills, wage-loss checks, attendant care, or replacement services after a crash, speak with a PIP benefits lawyer Dearborn as soon as possible. A lawyer can review the denial, gather medical and employment proof, communicate with the insurer, and help protect deadlines that may limit what overdue benefits you can recover.
Michigan Personal Injury Protection, or PIP, pays certain first-party benefits after an auto accident regardless of who caused it. But insurers may question whether treatment is necessary, dispute wage-loss calculations, or demand more records. Dearborn residents also need to understand how their chosen PIP medical coverage level, health insurance, and Michigan’s no-fault rules affect a claim.
I am Jalal Abdallah, a Michigan attorney and licensed insurance producer with property and casualty licensing, which gives me practical insight into insurance coverage and claim issues. As a PIP benefits lawyer Dearborn residents can turn to, I help injured people understand their options before moving into the details of Michigan no-fault benefits.
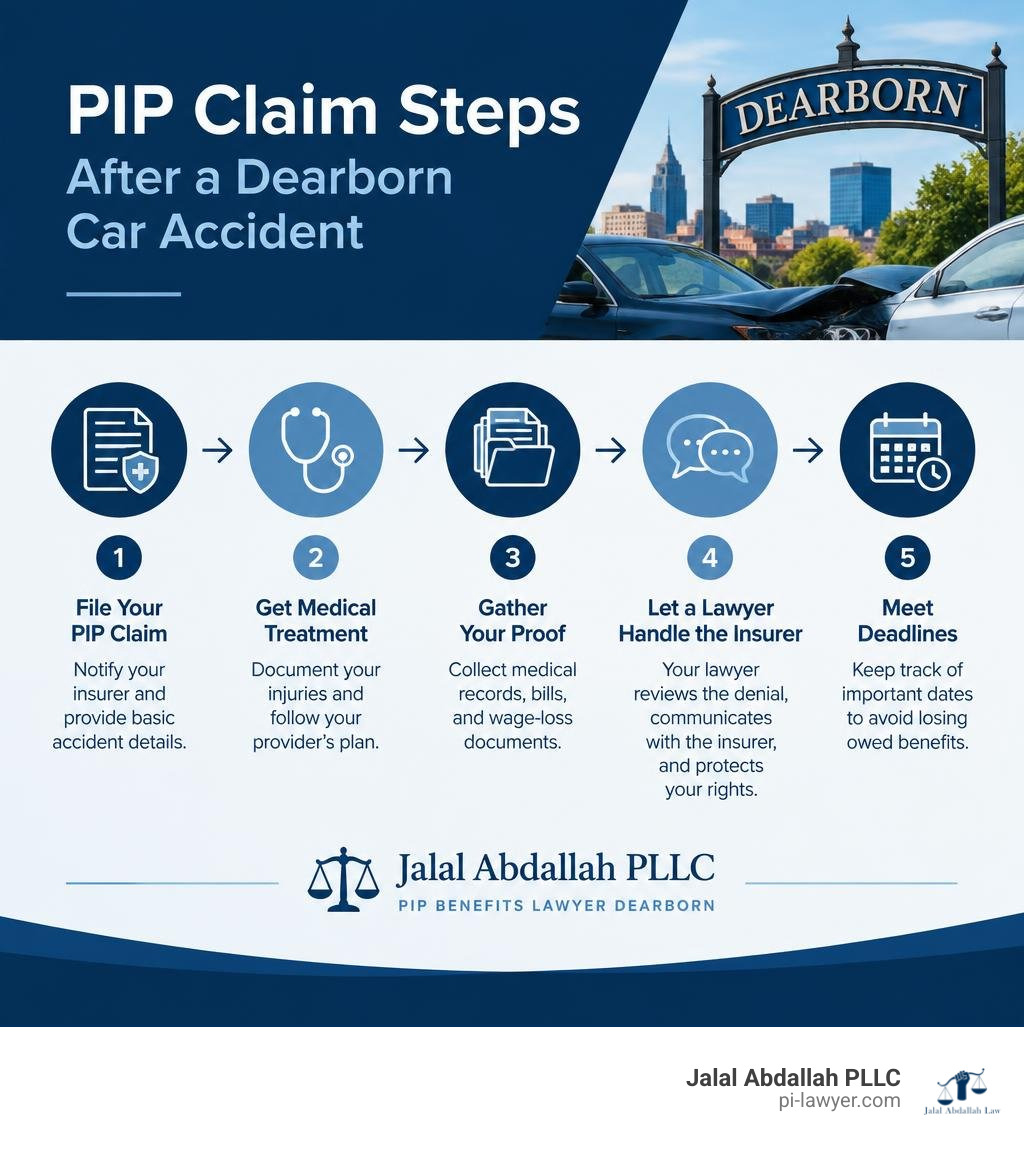
Easy PIP benefits lawyer Dearborn glossary:
Understanding Michigan No-Fault Insurance and PIP Benefits in Dearborn
Under the Michigan No-Fault Act, every auto insurance policy is designed to provide immediate economic support after an auto accident. When a crash occurs along busy corridors like Michigan Avenue, Telegraph Road, or Ford Road in Dearborn, victims must turn to their own auto insurance carriers first. These economic protections are known as first-party Personal Injury Protection (PIP) benefits.
Unlike third-party liability lawsuits that hold the negligent driver accountable for non-economic damages, PIP benefits apply regardless of who was at fault for the crash. Knowing what to do immediately after a car accident in Michigan ensures you take the right steps to secure these benefits without compromising your rights.
Michigan PIP covers four primary categories of economic losses:
- Allowable Medical Expenses: Coverage for all reasonable and necessary medical treatments, rehabilitation, surgeries, medications, and medical transportation.
- Work Loss Reimbursement: Payment of up to 85 percent of your gross lost wages for up to three full years from the date of the crash, subject to a statutory monthly maximum.
- Replacement Services (Household Chores): Reimbursement of up to $20 per day for services the injured person would have performed for themselves and their dependents, such as cooking, cleaning, or childcare.
- Attendant Care: In-home nursing care or aide services required for daily living tasks, which can be performed by professional agencies or family members.
To establish who pays these benefits, we analyze Michigan’s strict priority rules under MCL 500.3114. Typically, your claim proceeds in this order:
- Your own auto insurance policy
- Your spouse’s auto policy
- An auto policy held by a relative residing in your household
- The Michigan Assigned Claims Plan (MACP) if no other coverage exists
Understanding the difference between first-party benefits and third-party claims is essential when evaluating the total value of your recovery. While first-party claims handle your medical bills and lost income, you may also pursue compensation for pain and suffering from the at-fault driver if your injuries meet the state’s serious impairment threshold. You can review understanding pain and suffering damages in personal injury cases to see how non-economic recoveries operate alongside PIP benefits.
| Benefit Feature | First-Party PIP Benefits | Third-Party Tort Claims |
|---|---|---|
| Fault Requirement | Payable regardless of fault | Must prove another driver was negligent |
| Primary Payer | Your auto insurer (or priority insurer) | At-fault driver’s insurance carrier |
| Medical Expenses | Reasonable and necessary medical care | Covered if exceeding chosen PIP limits |
| Wage Loss | 85% gross wages up to 3 years | Excess wages beyond 3 years or policy caps |
| Pain and Suffering | Not covered under PIP | Covered if threshold injury is met |
| Household Services | Up to $20 per day for up to 3 years | Not standard; factored into overall damages |
Medical Coverage Tiers and Attendant Care Caps
Following Michigan’s major no-fault insurance reforms, drivers can choose specific PIP medical coverage levels when purchasing policies:
- Unlimited PIP Medical: Covers all lifetime allowable expenses.
- $500,000 Cap: Covers medical expenses up to half a million dollars.
- $250,000 Cap: Limits total medical recovery to a quarter of a million dollars.
- $50,000 Cap: Available exclusively to drivers enrolled in Medicaid.
- PIP Medical Opt-Out: Available to drivers with qualifying Medicare coverage.
These reforms also introduced complex medical fee schedules that dictate what doctors and hospitals can charge insurers. For family members providing in-home attendant care, the law limits reimbursable care to 56 hours per week unless the insurance company explicitly agrees to authorize more. When complex injuries require sustained support, coordinating private healthcare, auto coverage, and potential long-term benefits is critical. In cases involving severe, disabling injuries that halt long-term employment, Jalal Abdallah PLLC can help you understand how total disability claims may affect your recovery.
Why You Need an Experienced PIP Benefits Lawyer Dearborn After a Crash

Insurance adjusters frequently look for technicalities to delay or deny payouts. In Dearborn, disputed claims often head to local courtrooms, such as the 19th District Court of Dearborn for smaller claims or the Wayne County Circuit Court for larger disputes. When insurers act in bad faith or withhold valid payments, an experienced advocate steps in to force compliance with Michigan statutory rules. You can review our car accident lawyer Dearborn guide to learn how local courtroom familiarity protects injured claimants.
Insurers employ complex strategies to limit their liability, which is why understanding how insurance companies try to devalue your injury claim gives you an advantage during negotiations. When you partner with us at Jalal Abdallah PLLC, we stand between you and the aggressive insurance adjusters trying to cut off your lifeline.
How a PIP Benefits Lawyer Dearborn Handles Denied Attendant Care
A common obstacle in Michigan no-fault claims is the insurer-hired medical examiner. Insurance companies frequently schedule an “Independent Medical Examination” (IME)—which is rarely independent. These doctors review your records during a brief exam and produce reports claiming you no longer require attendant care, wage loss, or physical therapy.
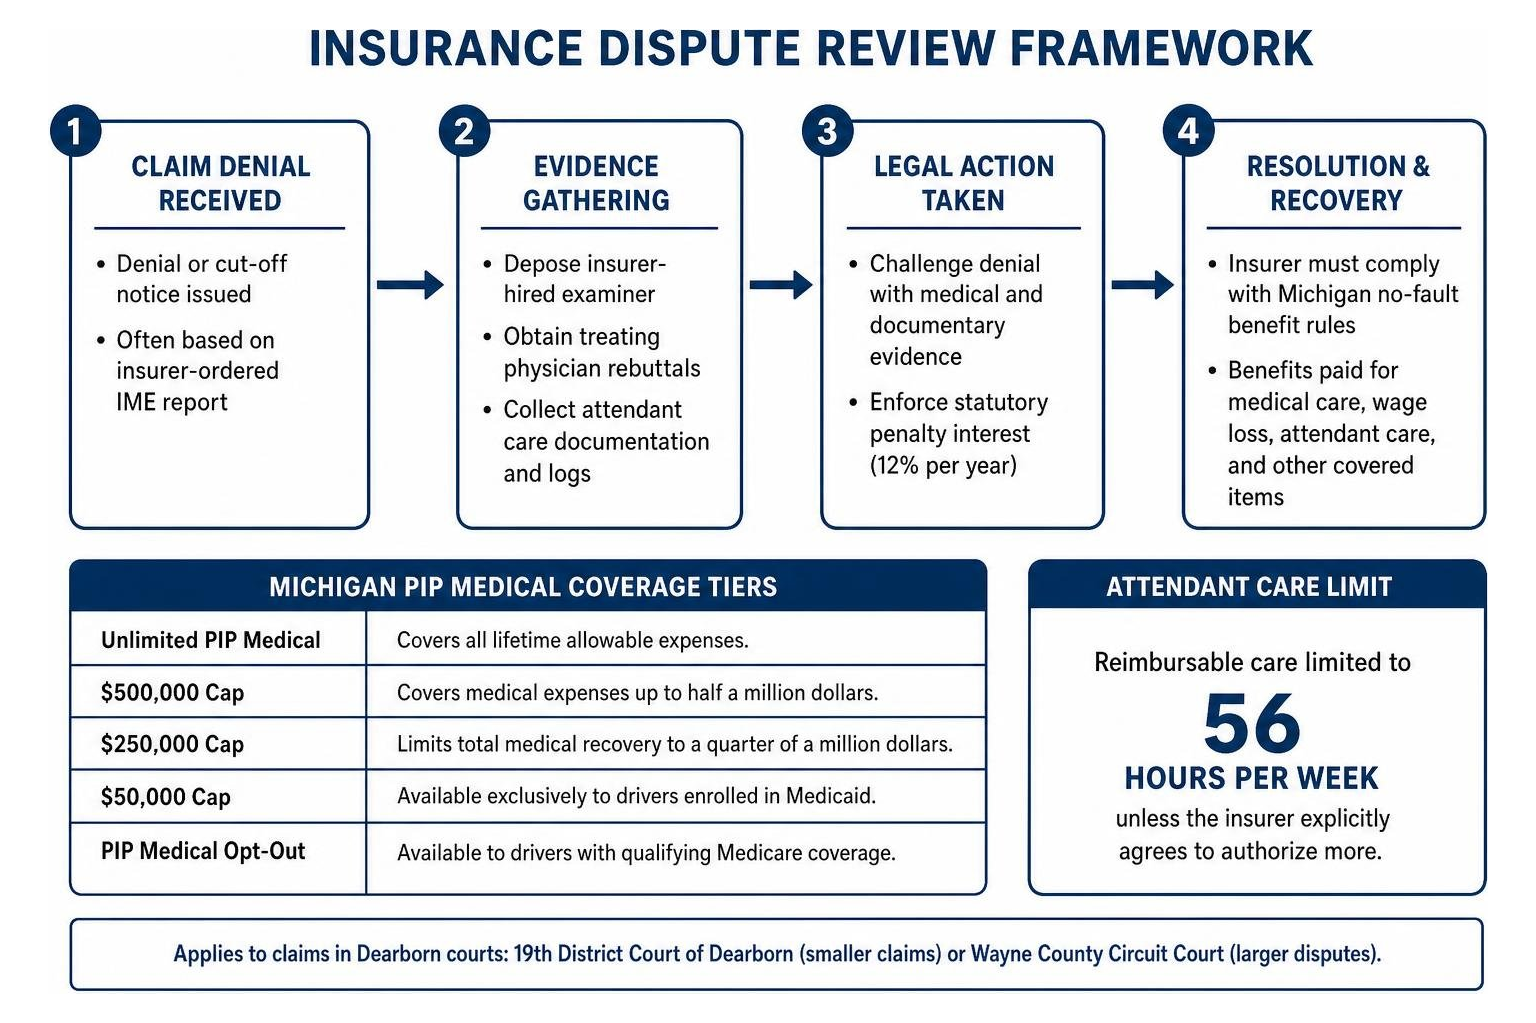
When an insurer issues a cut-off notice based on an IME, we take immediate action:
- We depose the examiner to expose biases, including their history of paid work for auto insurers.
- We work with your treating physicians to draft detailed medical rebuttals explaining why ongoing care is necessary.
- We compile detailed attendant care affidavits, service logs, and caregiver time cards.
- We enforce statutory penalty interest under MCL 500.3142, which requires insurers to pay 12% annual interest on overdue, improperly denied claims.
Navigating the Strict One-Year Back Rule and Filing Deadlines
Timing is critical under the Michigan No-Fault Act. Under MCL 500.3145, two separate deadlines govern your PIP claim:
- Written Notice of Injury (One-Year Notice): You must give formal written notice of your injury to the correct auto insurer within exactly one year of the crash. If this notice is not submitted, your claim is barred forever.
- The One-Year-Back Rule: In a lawsuit for overdue benefits, you cannot recover benefits for any medical bill, wage loss, or service incurred more than one year before the date the lawsuit is filed.
While recent statutory amendments allow the one-year-back period to pause (toll) between the date a formal claim is submitted and the date the insurer formally denies it in writing, insurers often issue vague correspondence to confuse claimants. We ensure all claims are formally preserved, properly categorized under our personal injury practice protocols, and filed before any deadlines expire.
Common Tactics Insurers Use to Deny Dearborn No-Fault Claims
Insurers employ various tactics to deny or reduce legitimate claims:
- Paper Reviews: Claim adjusters hire third-party doctors who never examine you to review your medical charts and declare treatments unnecessary.
- Delayed Wage Replacement Checks: Demanding endless employment verifications, prior tax returns, and employer statements to avoid issuing timely wage reimbursement.
- Refusing Medical Mileage and Transportation: Denying reimbursement for the gas, mileage, or transit costs required to travel to your medical appointments.
- Blaming Pre-Existing Conditions: Claiming that your back, neck, or joint pain stems entirely from degenerative aging or an old workplace injury rather than the motor vehicle collision.
When an insurer stonewalls valid payments, we assemble formal demand packages containing verified records, billing ledgers, and treating physician certifications. To see how these tactics apply across all motor vehicle accidents, review our overview of car accidents.
When to Consult a PIP Benefits Lawyer Dearborn for Maximum Recovery
You should reach out for legal support as soon as any of the following occur:
- An insurer fails to issue wage loss checks within 30 days of receiving proof.
- You receive a formal denial letter for surgeries, diagnostic MRIs, or therapy.
- Medical providers threaten to send unpaid accident bills to collections.
- An adjuster insists that you submit to an IME or an Examination Under Oath (EUO).
- You suffered catastrophic injuries, such as traumatic brain injuries or spinal trauma, that require coordinated lifetime care.
How to Choose the Right No-Fault Legal Advocate in Dearborn
Selecting the right attorney directly impacts whether your medical bills get paid and your family remains financially protected. You need legal counsel familiar with the Wayne County court system and experienced in dismantling insurer defenses. Using our ultimate checklist for hiring a Dearborn crash claim lawyer will help guide your decision.
We represent injured clients on a contingency fee agreement, meaning you pay no upfront fees, and we only collect legal fees if we recover benefits or compensation for you.
Critical Questions to Ask During Your Legal Case Evaluation
Before hiring an attorney, ask these key questions:
- What is your track record in overturning first-party no-fault claim denials?
- How do you handle medical fee schedule disputes with stubborn insurers?
- Will you help me manage ongoing wage loss and replacement service submissions?
- How frequently will your team provide updates regarding my case?
For a thorough look at how we review your potential claims, read our guide on Dearborn injury case evaluation everything you need to know.
Frequently Asked Questions About PIP Benefits in Dearborn
What do Michigan PIP benefits cover after an auto accident?
Michigan PIP benefits cover all reasonable and necessary medical treatments, up to 85% of gross lost wages for up to three years, up to $20 per day in replacement services for household help, transportation mileage to and from doctor appointments, and funeral and burial expenses in fatal crashes.
How long do I have to file a PIP benefit claim in Dearborn?
You must provide formal written notice of your injury to your auto insurer within one year of the accident. Additionally, under the One-Year-Back rule, any lawsuit for overdue benefits must be filed within one year of the date the specific expense or medical bill was incurred, subject to statutory tolling rules.
Can I receive PIP benefits if I was at fault for the accident?
Yes. PIP benefits are true “no-fault” protections. Regardless of whether you caused the collision, the other driver caused it, or adverse weather conditions contributed, you are entitled to your full first-party statutory medical, wage loss, and replacement service benefits under Michigan law.
Turn Denied Claims into Recovered Benefits
Dealing with denied medical coverage or delayed wage loss checks creates unnecessary stress when you should be focused on healing. Insurance carriers rely on strict deadlines and confusing paperwork to protect their profits, but you do not have to fight them alone. At Jalal Abdallah PLLC, we stand up for underdogs against aggressive insurance companies to overturn unjust claim denials and recover the benefits you are owed under Michigan law.
If your no-fault benefits have been cut off, reduced, or delayed, contact us today to take control of your recovery. Schedule a free PIP claim consultation with our team, and let us protect your rights and your household’s financial future.
Share This Article

Schedule Your Free Consultation Today!
Reach out today and receive a consultation, completely free of charge - we'll evaluate your case and let you know what comes next.


